

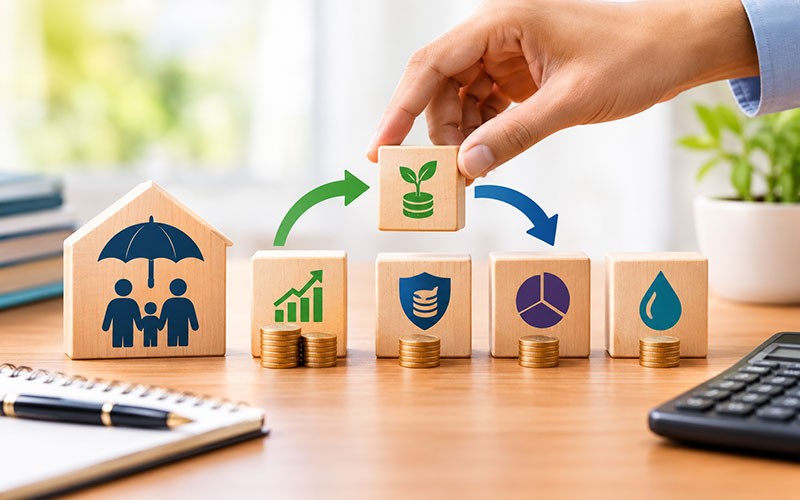
How ULIP Fund Switching Works and When Investors Typically Consider It
A Ulip plan folds life insurance together with market-linked investment. You can move the money around as the years go on. Fund switching is how you shift the accumulated value from one fund option to another and leave the policy intact. You do not have to surrender it.
Use that when your priorities have actually changed. A jumpy week on the screen is a weak reason on its own.
How Fund Switching Works in a ULIP Plan
A Ulip plan allows policyholders to move their investment from one fund to another within the same policy. The cover does not get rewritten. Allocation does.
Insurers differ. Some give you a set number of free switches in a year. After that, a nominal charge tends to apply.
Common fund options include:
- Equity funds, if the aim is higher growth over a long stretch and you accept the ups and downs that come with it.
- Debt funds. People usually pick these when they want more stability and less of the market’s swing.
- Balanced funds hold equity and debt in one place. The idea is a middle path on risk and return.
- Liquid or money market funds get used when you mainly want to protect capital for a short spell.
The life insurance cover is the same after the switch. Only where the invested money sits has changed.
When Do Investors Typically Consider Switching?
Timing is personal. It hangs on your circumstances and on the financial plan you already follow. A lot of investors reopen the allocation at a big life stage, or after the market has moved hard.
Typical situations include:
- Changing financial goals. Saving for a child’s education, or heading toward retirement, can mean you need a different risk profile than before.
- Market volatility. One camp cuts equity when the period feels uncertain. Another camp adds equity bit by bit after a correction.
- Investment horizon. Once fewer years remain on the policy, the mix often turns more conservative.
- Portfolio rebalancing. A strong run can leave too much on the growth side and too little on the stable side. Switching is how some people restore the split they first wanted.
Looking at the policy now and then, on your own timetable, usually beats answering a headline.
Key Factors to Evaluate Before Switching
Ask the dull question first: does this request still fit the wider strategy?
Consider these points:
- Risk tolerance. Are the old swings still acceptable, or has that changed?
- Long-term objective. Will the new mix do a better job for the goals ahead?
- Fund performance. Ignore the latest burst. Check whether results have been consistent over time.
- Charges and limits. Read the insurer’s switching rules. Note any fee.
- Overall asset allocation. The ULIP sits inside a larger pile of investments. The switch should work with that pile.
Sit with those five before you tap submit. Constant, mood-led switching is what tends to interrupt long-term wealth building.
Conclusion: Switch with Purpose, Not Panic
Being able to move between funds is one of the real advantages of a Ulip plan. The useful version of that feature is not market-guessing. It is keeping the money lined up with goals that have evolved, with the risk you can still carry, and with the time left on the policy.
Review on a regular basis. Make the change when the plan calls for it. Use the switch as a planning tool. Do not use it as a reply to a short burst of market noise.
Support Our Journalism
We cannot do without you.. your contribution supports unbiased journalism
IBNS is not driven by any ism- not wokeism, not racism, not skewed secularism, not hyper right-wing or left liberal ideals, nor by any hardline religious beliefs or hyper nationalism. We want to serve you good old objective news, as they are. We do not judge or preach. We let people decide for themselves. We only try to present factual and well-sourced news.
Support objective journalism for a small contribution.